Full Professor of Actuarial Science, HEC Lausanne. I work on extremes, random fields and regular variation, and on the probability that underlies insurance and risk.
My research focuses on stochastic analysis and applied probability, particularly rare events, extremes of random fields, regular variation, shift-invariant structures, multivariate dependence, and representations of asymptotic constants. Drawing on my actuarial expertise and industry experience at Allianz Suisse, I also work on applied problems in non-life insurance, risk management, and financial mathematics.
Together with Krzysztof Dębicki and our teams, I have developed a theory of rare events for vector-valued Gaussian random fields, including the asymptotic constants governing their extremal behaviour.
Before joining the University of Lausanne, I led the non-life insurance pricing team at Allianz Suisse Insurance. I have been a qualified actuary of the Swiss Association of Actuaries (SAA) since 2004 and have served on its Education Committee since 2011.
I completed my PhD at the University of Bern in 1999 under the supervision of Professor Jürg Hüsler, received the Venia Docendi in Applied Stochastics from the University of Bern in 2004, and hold the title of Privatdozent.
Editorial boards
Journal of Applied Probability
Advances in Applied Probability
Probability and Mathematical Statistics
Statistics & Probability Letters
Spanish Journal of Statistics
Positions & education
Present
Professor of Actuarial Science, HEC Lausanne, UNIL
since 2011
Education Committee, Swiss Association of Actuaries
since 2004
Privatdozent, applied stochastics, University of Bern; qualified actuary (SAA)
2005–2010
Head of non-life pricing, Allianz Suisse
2000–2005
Reserving actuary, Allianz Suisse
1999
PhD, University of Bern (advisor: Jürg Hüsler)
1994–1996
Actuary, INSIG, Tirana
Probability, illustrated
Explore objects from recent papers: move a slider, resample a path, and see what changes. These four illustrations are a starting point; the gallery has all fifteen.
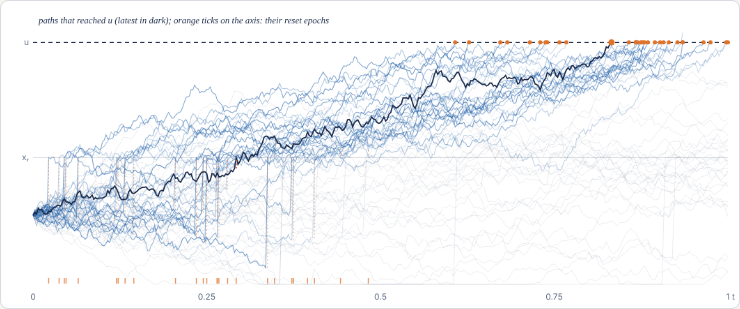
Animated: Brownian motion sent back to xR at Poisson times. Explore how the reset rate affects the search for a level u, the asymmetric Laplace steady state, and the different high-level tail regimes for positive and non-positive reset points. From Dębicki, Hashorva & Michna.
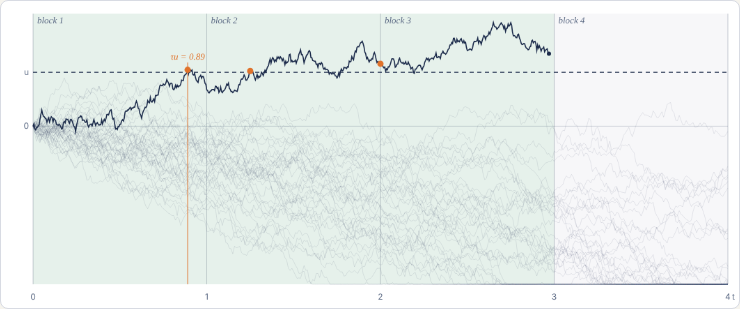
Animated: Brownian paths rain down until one exceeds u in each of m reporting blocks, or in every sliding window of length h. At high levels the first hit crowds against h; each ruin probability has the one-block Gaussian tail scale multiplied by its own constant. From Dębicki, Hashorva & Michna.
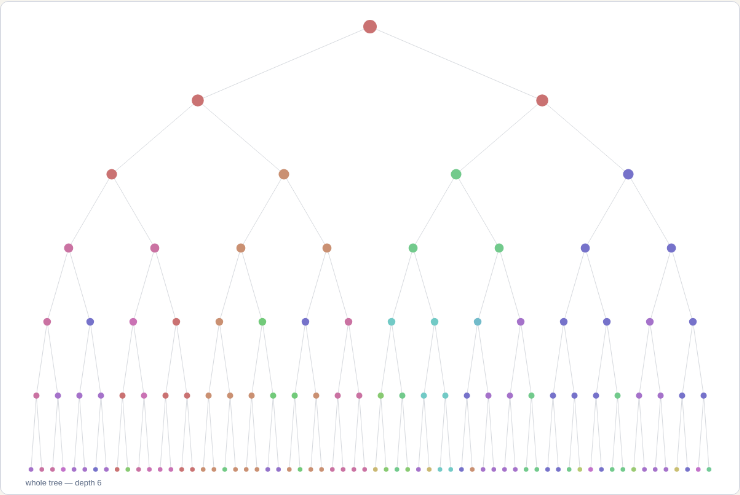
Brown–Resnick construction driven by a Gaussian branching random walk. Colours show which Poisson point wins at each vertex. Explore the branch-stationarity of the full model through a finite simulation.
Turn the roughness α of a Gaussian field from 2 downwards: the Euler-characteristic heuristic gives way to Pickands–Piterbarg asymptotics and the constant ℋα. A companion to Pavel Ievlev's illustration.